
🏡 Is the 50-Year Mortgage the Key to Unlocking Affordable Homeownership? An Expert Weighs In
Housing affordability is a hot topic, especially for first-time buyers and families looking to escape the rental trap. One concept gaining attention as a potential solution is the 50-year mortgage.
As the founder of OwnerWebs.com and a licensed real estate broker with two decades of experience in the vacation rental industry, I've watched countless market shifts. When a change like this is proposed, the natural question for current and prospective homeowners is: What will this mean for me?
Recently, I was asked to weigh in on the potential impacts of a 50-year mortgage on the housing market, particularly how it affects qualification, equity, and selling a home. Here are my insights on this controversial concept.
1. Does a 50-Year Mortgage Make Qualification Easier or More Difficult?
The core qualification standards—like good credit and a low debt-to-income (DTI) ratio—will likely remain the same. Lenders still need to ensure you can support the monthly expense.
However, the major change is the monthly note size.
- The Benefit: A longer term, like 50 years, significantly reduces the required minimum monthly payment. This lower note means a borrower can qualify with a lower income or DTI ratio than they would for a standard 30-year term.
- The Outcome: I believe the difficulty to qualify will remain consistent with current standards, but the lower note will offer significant relief for buyers, potentially making housing more accessible and affordable on a month-to-month basis.
2. How Will This Affect First-Time Homebuyers?
First-time homebuyers stand to be the most impacted—and, in my view, in a positive way.
Housing affordability has become a crisis across the country. Many, including younger generations, are finding the American Dream seemingly impossible to reach. The 50-year mortgage could be the tool that allows more first-time buyers to finally get their foot in the door.
- Escaping the "Rent Trap": A lower monthly payment could allow more individuals and families to transition from renting (where payments build zero equity) into owning (where at least some equity is gained over time). I believe first-time buyers will be more easily qualified because of the lower monthly note.
3. What’s the Impact on Interest Over the Course of the Loan?
This is where buyers need to be most aware. While the interest rate itself is market-driven and will fluctuate just like any other financial product, the amortization schedule is key.
Lenders collect the vast majority of their interest money in the front of the loan, not the back. Extending the term allows them to draw out this interest period even further.
Let’s look at a simple example with a $300,000 mortgage at 6% interest:
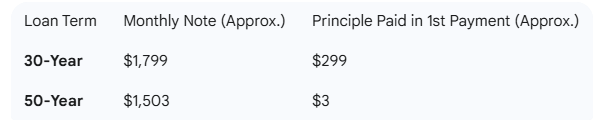
The Takeaway: The buyer enjoys significant affordability with the 50-year note, but gaining meaningful equity in the home will be much slower and more difficult due to the minimal principle reduction in the early years.
4. What Does This Mean for Sellers Who Want to Move Quickly?
For current homeowners looking to sell and move quickly, the 50-year mortgage could be beneficial, at least initially.
- Wider Buyer Pool: Sellers will be exposed to a larger pool of qualified buyers due to the increased affordability. This increased demand could make the selling process easier and faster.
- Buyer Benefit: Buyers who use this option and then move after a few years may have gained some equity, which is still better than the zero equity gained by renting.
5. Will the 50-Year Mortgage Eventually Make It Harder to Sell a Home?
In the short term, the market will likely become easier for sellers. However, we must proceed with caution and learn from history.
Increased demand drives up prices.
We saw this exact scenario play out during the COVID-19 pandemic in 2020. Interest rates dropped dramatically, which created a massive pool of new homebuyers. While the interest rate savings were substantial, the sheer demand caused housing prices to literally double in some markets. Here in 2025, prices still haven't returned to pre-COVID levels.
- The Risk: Introducing a 50-year mortgage could create a similar market effect. All of the benefits of a lower monthly payment and increased affordability could be erased if the cost of housing simply increases to match the new, larger pool of qualified buyers. This increased demand drives up prices, making the total home cost unaffordable, regardless of the lower monthly note.
Final Thoughts for OwnerWebs Customers
While a 50-year mortgage could provide a much-needed affordability boost for many, especially first-time buyers, it’s not a magic bullet. For those of you who own vacation rental properties, the key takeaways are:
- Increased Demand: More qualified buyers in the market could translate to higher property valuations over time, which is good for your investment.
- Equity is Slower: For buyers using this option, be aware that equity gain will be minimal in the beginning.
As an OwnerWebs customer, you are already ahead of the curve by running a profitable, book-direct website for your investment. Stay informed about these financial trends, as they directly impact the value and profitability of your real estate portfolio.
Frequently Asked Questions
What is the main benefit of a 50-year mortgage?
Will a 50-year mortgage make it easier to qualify for a home loan?
How does a 50-year mortgage affect home equity?
How much more interest will I pay over the life of the loan?
Will the interest rate be higher on a 50-year mortgage?
Will a 50-year mortgage help first-time homebuyers?
How would this change affect the speed of selling a home?
Could the 50-year mortgage drive up housing prices?
If I sell after a few years, will I have any equity with a 50-year loan?
Who benefits most from the introduction of a 50-year mortgage?
Matthew Thompson
Matthew Thompson is a licensed employing real estate broker in Louisiana and Colorado, with twenty years of experience in the vacation rental home industry. He holds a degree in Chemical Engineering from Louisiana Tech University and is also the developer and founder of OwnerWebs.com, a vacation rental website builder. View his professional profile